

Nonrefundable nationality contributions and approved property investments can support lawful citizenship applications, but their economics differ substantially, making capital recovery, government screening, family costs, and long-term mobility objectives essential considerations for international applicants.
WASHINGTON, DC, November 6, 2026 — Applicants comparing citizenship-by-investment programs increasingly encounter two financial arrangements that may share the same advertised entry price but create fundamentally different expectations about ownership, liquidity, financial returns, and the permanent transfer of wealth.
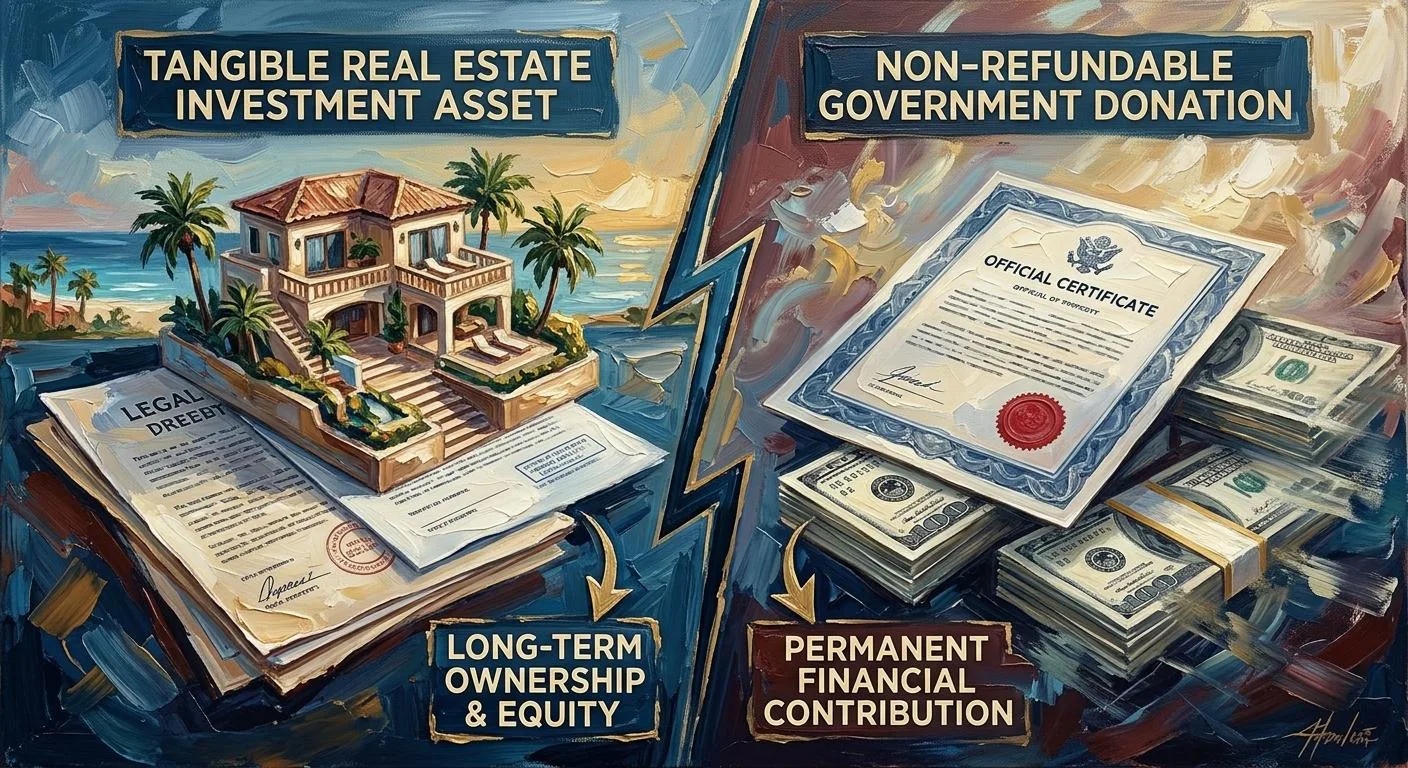
A donation to an authorized government development fund ordinarily becomes a nonrecoverable contribution once completed, whereas an eligible real estate investment may represent an asset that can eventually be sold, although neither route guarantees citizenship approval or favorable investment performance.
For families evaluating another nationality, the difference requires examining the entire transaction rather than the minimum advertised amount, because professional charges, dependent fees, holding restrictions, and future residence plans can change each route’s practical value.
A Citizenship Donation Is Not a Conventional Portfolio Investment
A conventional investment in ordinary financial markets usually involves acquiring an asset or contractual interest with some possibility of income, capital appreciation, or repayment, although the expected outcome remains subject to business, market, and counterparty risks.
A citizenship donation instead transfers money to a qualifying public fund under government program rules, without generally providing the applicant with shares, a repayment entitlement, or a transferable interest in the development projects supported by that contribution.
Marketing materials that describe both arrangements as investments can therefore blur an important economic distinction, especially when readers assume that a government contribution will behave like a property purchase or financial security after nationality has been granted.
Dominica Provides a Clear Comparison of the Two Routes
Dominica’s official Citizenship by Investment Unit states that its Economic Diversification Fund requires a nonrefundable contribution beginning at US$200,000 for one applicant, with additional amounts and charges depending on the household’s qualifying composition.
The same authority lists a minimum US$200,000 investment in an approved real estate development, but that property route involves separate government fees and a required holding period before an eligible ownership interest may be sold.
Those matching entry thresholds do not make the two financial choices equivalent, because the donation ordinarily has no capital recovery mechanism while a property interest introduces ownership costs, possible proceeds, and substantial uncertainty about resale value.
Regional Scrutiny Adds a New Dimension to Program Decisions
An October 29, 2026, widely circulated Reuters report on European pressure surrounding Caribbean investor citizenship examined negotiations involving Antigua and Barbuda and neighboring states whose citizenship revenues support government budgets and development activity.
European authorities have pressed several Eastern Caribbean governments to phase out their programs, while regional leaders have emphasized the economic importance of contribution receipts and the potential disruption associated with losing access to European visitor markets.
These developments matter to both donors and property investors because international visa arrangements can change independently of citizenship recognition, and program uncertainty may affect future demand for qualifying developments without making approved passports automatically invalid.
Nonrefundable Means the Contribution Should Be Budgeted as Spent
A household choosing a government-funded contribution should generally assess the required amount as a permanent expenditure rather than money expected to finance retirement, produce monthly income, or become available again for another investment.
An applicant may obtain valuable nationality rights after successful government approval, but the legal benefit is not a cash-equivalent asset, and its subjective usefulness cannot be entered into a financial plan as a guaranteed monetary return.
Consequently, the relevant household affordability question is whether the family can part with the contribution while retaining sufficient reserves for ordinary living costs, emergencies, education, and any intended move following the nationality decision.
An Approved Property Interest Has a Different Risk Profile
A qualifying real estate purchase may leave the applicant with a legal interest that could eventually be transferred or sold, but ownership does not mean the investment will maintain its original market value.
Hotel developments and resort projects can experience construction delays, weak occupancy, operating losses, financing difficulties, and management disputes, any of which may affect distributions or the ability to find an acceptable future buyer.
Investors should distinguish the property’s official eligibility for a citizenship program from independent evidence of its commercial viability, because government recognition of an approved project does not guarantee profit or capital recovery.
Holding Periods Can Restrict Access to Capital
Dominica’s official rules generally require qualifying citizenship real estate to be held for at least three years after citizenship is granted, restricting an owner’s ability to dispose of the interest immediately when circumstances change.
Where the same property is intended to qualify a subsequent citizenship-by-investment applicant, the relevant holding period is generally five years, creating a further distinction between permissible resale and reuse within the nationality program.
A family that may need funds for a business emergency or relocation should review those restrictions before purchasing, especially when the proposed asset is far less liquid than savings in a conventional bank account.
Property Resale Is an Opportunity, Not a Guaranteed Exit
The ability to sell after the required holding period depends on market conditions, contractual arrangements, transfer restrictions, buyer demand, and the project’s financial circumstances, rather than merely the expiration of a government-mandated deadline.
An applicant who pays US$200,000 for a qualifying property interest might recover more, less, or none of that amount in a later transaction, depending on the investment’s structure and the circumstances prevailing at resale.
Projected rental distributions should likewise be treated as assumptions requiring evidence, because attractive marketing illustrations do not establish that revenue will cover fees or that distributions will continue through an entire holding period.
The Full Cost Often Exceeds Either Starting Threshold
Donation applicants may also owe additional processing, background screening, interview, naturalization certificate, passport issuance, translation, and professional assistance charges beyond the principal contribution required by the government for the selected family category.
Property applicants can also face many of those same citizenship-related charges and expenses, plus government property-route fees, transaction expenses, maintenance obligations, and potentially professional costs tied to the ownership structure and eventual sale.
The correct comparison therefore examines total expected cash outflows and realistic recovery assumptions across both routes, rather than placing two US$200,000 minimum amounts side by side as though they represented identical financial commitments.
Family Composition Can Change the Economics Considerably
A single investor’s quoted minimum rarely captures the costs for a spouse, children, or older qualifying dependents, because governments apply eligibility criteria and may assess different contribution or due diligence charges across family categories.
An adult dependent approaching an age threshold may require a different documentary assessment from a young child, while a relative who does not qualify under the program cannot automatically obtain citizenship through the principal applicant’s payment.
Families should calculate each participant’s legal eligibility and full fees before choosing a financial route, especially when the stated objective is to establish future relocation rights for an entire household rather than one person.
Government Screening Remains Necessary Under Both Options
Dominica’s citizenship authority makes clear that choosing approved property does not remove the due diligence requirements for donation applicants, including identity verification and a relevant examination of the applicant’s background and financial circumstances.
Applications proceed through authorized representatives and government assessment, with required interviews and other checks applying under the current rules, meaning investment capacity alone cannot compel a favorable nationality decision from the issuing authority.
A responsible professional adviser should clearly explain the review stages and potential refusal risks before payment rather than suggesting that purchasing a property interest or contributing to a public fund bypasses official scrutiny.
Payment Timing Matters Alongside the Financial Amount
Dominica’s published process generally places completion of the qualifying contribution or approved property investment after an applicant receives approval in principle, distinguishing initial documentation and screening from final fulfillment of the investment requirement.
Prospective applicants should independently confirm precisely which charges arise earlier, which amounts may become nonrefundable, and what contractual protections apply if a separate real estate transaction cannot be completed after the government review.
Detailed written payment milestones can reduce confusion when several entities receive payments, but an agent’s receipt or a provisional approval letter should not be mistaken for citizenship already conferred by the responsible government.
The Issuing Country’s Economic Objectives Are Relevant
Government contribution funds can support essential long-term national public projects involving infrastructure, education, health services, or resilience, giving governments a revenue source that differs from privately owned property investments within approved commercial developments.
The public-policy rationale for such programs does not, however, transform a donor’s contribution into a financial instrument, because anticipated benefits to the national economy are not the same as contractual distributions to an applicant.
Applicants who value directly supporting the destination’s national development may regard that objective as meaningful, while others primarily concerned with capital preservation may prefer to evaluate an asset-based route and its associated uncertainty.
Visa-Free Privileges Should Not Be Treated as Investment Yield
Another nationality may permit temporary visits to destinations that otherwise require advance visas, but those arrangements depend on foreign governments and can change without producing compensation for a citizenship contribution or property purchase.
The international pressure reported around Caribbean citizenship programs illustrates this risk, particularly where European access features prominently in marketing even though the issuing country cannot independently guarantee the continuation of another region’s visa waiver.
A household should therefore value potential travel convenience according to actual planned journeys and lawful residence rights, rather than assigning an assumed permanent financial return to today’s passport ranking or promotional access map.
Residence Rights Can Have Personal Rather Than Market Value
For an applicant intending to settle permanently in the issuing country, the right to reside and work may justify a substantial nonrecoverable contribution even when no rental income or eventual sale proceeds are expected.
Another applicant who chiefly wants a contingency document for occasional travel may calculate the benefit differently, particularly if the family has no concrete plans to live in that jurisdiction or pursue employment there.
Neither legitimate personal household objective determines a universal financial choice, since the appropriate assessment depends on household wealth, expected mobility, personal security priorities, and willingness to accept investment risk or permanent capital expenditure.
American Applicants Must Evaluate Continuing Obligations
The United States Department of State’s official dual nationality guidance explains that American citizens generally retain legal responsibilities in the United States after acquiring another nationality and must use American passports to enter and leave their home country.
A Caribbean passport does not automatically change tax residence, remove financial reporting obligations, or provide anonymous access to regulated banking services, even if citizenship was obtained through a contribution or eligible property purchase.
Cross-border financial advice may be particularly important where an applicant owns businesses, trusts, or substantial investments, because the taxation and reporting consequences of holding property abroad require analysis distinct from the citizenship application.
Document Authentication Cannot Prove Investment Performance
Modern biometric passports include electronic security features that compatible systems can inspect, but technical authentication of a document cannot establish that an associated property investment is profitable or that the original contribution should be recoverable.
Amicus International Consulting discusses these distinctions in its guide on how to scan a passport’s NFC chip and understand the results, distinguishing electronic document checks from underlying citizenship decisions and current government recognition.
A successful electronic passport inspection may reasonably support greater confidence in a passport’s security features, but it cannot replace independent verification of property ownership, contractual protections, or official citizenship eligibility.
Program Changes Can Affect the Financial Calculation
Official government contribution thresholds, frequently changing lists of approved investment projects, dependent definitions, and administrative charges can change, leaving older promotional brochures unreliable for a family making a decision under rules currently in force.
Carefully recheck current official terms immediately before applying, particularly where international negotiations may affect future program operation or demand for property marketed primarily to prospective investor citizens.
Prospective investors should carefully consider whether an unfavorable regulatory development would leave them comfortable with their remaining property exposure or a completed nonrefundable payment, without assuming that citizenship automatically disappears after a policy change.
Professional Advice Should Cover Both Law and Finance
An authorized citizenship agent can coordinate a complex citizenship program application, but independent legal and investment specialists may be needed to evaluate property contracts, beneficial ownership, taxes, financial risk, and family succession arrangements.
The applicant should request transparent written identification of government fees, agent compensation, property charges, expected distributions, exit restrictions, and any scenarios in which additional payments may be required before ownership can be transferred.
A transparent financial comparison clearly separates the certainty of losing a completed donation from the uncertainty of future property returns, while recognizing that successful government screening remains a separate prerequisite under either route.
A Financial Decision Should Reflect the Applicant’s Actual Goal
Citizenship by donation can make sense as a deliberate expenditure for lawful nationality benefits, while approved real estate may appeal to applicants who accept longer commitments and uncertainty in pursuit of possible capital recovery.
Neither option should be marketed as guaranteed financial gain, and both require assessment of full fees, official approval, family eligibility, travel privileges, and the practical advantages of holding citizenship in the selected country.
Ultimately, citizenship donations differ from conventional investments because the first generally transfers money permanently for a potential nationality benefit, while the second involves an asset whose eventual value depends on commercial outcomes outside the passport approval process.